HRU MORTGAGE INVESTMENT CORPORATION
Investment Fund
Series B-1.
Monthly income. Real estate security.
An investment built around your future.
THE OFFERING
Product details.
HRU MIC Investment Fund Series B-1 provides mortgage borrowing solutions to Canadian Citizens, New Immigrants, and Non-Immigrants. Through property security on first or second mortgages, the fund focuses on the purchase, refinance, bridge, and renovation. This solution utilized high diversification to create a consistent and timely return. Base on HRU Financials’ strict and precise underwriting guidelines, we adapt to a decentralized risk model and mortgage combination to maximize our performance and minimize our risk. Our loan to value on the portfolio is a maximum of 80% only. With mortgage terms typically less than a year, we can adjust our lending and portfolio actively to avoid potential future risks.
INVESTMENT PLANS
Account availability is subject to the applicable plan, trustee and offering terms.
01 / SECURED ASSETS
Secured assets.
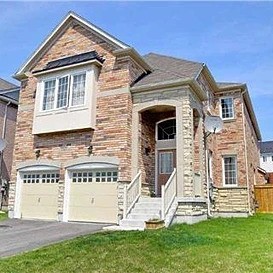
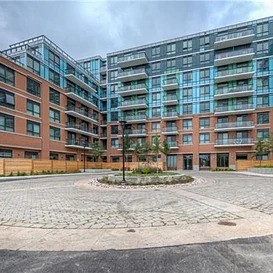
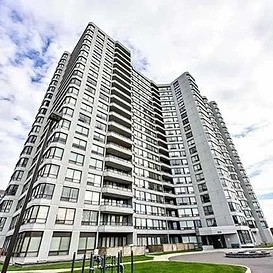
HRU MIC Investment Fund Series B-1 is designed to diversely invest in quality real estate property located in the greater ontario area. Historical Portofio Detail Below:
02 / LOAN TO VALUE
Loan to value.
Loan to Value is the ratio between mortgages and property market value, the best-managed loan to value can significantly lower risk for our investors and secure asset value against investment. HRU MIC Investment Fund B-1 concentrates its loan-to-value at approximately 80%, for example, if the borrower has a property appraised at $1 million, the maximum summation of all mortgages is around $800,000. It effectively decreases the mortgage default risk.
PORTFOLIO SNAPSHOT
One portfolio. A wider perspective.
Marketing presentation · August 31, 2026
The combined, principal-weighted LTV is 61.06%. The remaining 38.94% illustrates the equity portion relative to property value.
An aggregate illustration, not a measure of recoveries or a guarantee against loss. Individual loans and valuation dates vary.
Scale figures above are from the marketing presentation dated August 31, 2026. Loan data: September 2026 and May 12, 2026 snapshots. The combined display uses source snapshots from different dates, not a single current valuation. Chart figures are calculated from 135 itemized positive-balance loans. LTV uses each source’s reported loan LTV weighted by its listed principal; mortgage allocation uses the same principal balances.
03 / PROPERTY DISTRIBUTION
A local view.
A wider reach.
Our Invested Properties are across Ontario, this risk management method of geographical diversification lowers our risk of market fluctuation drastically. Historical Data are below:
EXPLORE THE LOCATIONS
Real estate across Ontario.
Loading the portfolio map…
View locations by municipality
- Ajax1
- Algonquin Highlands1
- Angus3
- Arden1
- Barrie17
- Bracebridge2
- Bradford1
- Brampton2
- Chelmsford1
- Collingwood3
- Concord1
- East Gwillimbury1
- Elmvale1
- Etobicoke1
- Holland Landing1
- Innisfil3
- King City1
- Kleinburg1
- Lefroy1
- London1
- Markham12
- Midhurst1
- Midland1
- Milton1
- Mississauga3
- Newmarket1
- Niagara Falls1
- North York4
- Oakville1
- Orangeville1
- Orillia6
- Oro-Medonte3
- Oshawa1
- Owen Sound2
- Parry Sound1
- Peterborough1
- Pickering1
- Port Carling1
- Richmond Hill5
- Scarborough2
- Shelburne1
- Springwater1
- Stayner1
- Stouffville2
- Sudbury1
- Tay Township1
- The Blue Mountains1
- Thornhill1
- Thornton1
- Tiny1
- Toronto22
- Vaughan6
- Wasaga Beach2
- Waterloo1
- Whitby2
- Woodbridge1
The combined display uses source snapshots from different dates, not a single current valuation. All 138 listed collateral locations appear in one map. Duplicate listed properties are combined; markers use municipality-level display positions.
04 / INVESTMENT GROWTH
Put your plans
in perspective.
Explore how principal, monthly contributions and interest could grow over time. Adjust the assumptions to see the difference between reinvesting and receiving income.
YOUR GROWTH, VISUALIZED
See what time could add.
Projection only, using a constant nominal annual rate paid monthly. Contributions enter at the start of each month. 8% is a target, not guaranteed. Taxes, fees, changing rates, losses and redemption restrictions are excluded. This is not historical fund performance or a promise of return. Monthly additions are illustrative and remain subject to subscription terms.
05 / INCOME TAX ACT
Income Tax Act.
To maintain our status as a Mortgage Investment Corporation (MIC), we must comply with strict regulations outlined in the Canadian Income Tax Act (subsection 130.1[6]).
Learn more about the Income Tax Act
- We can only invest or manage funds, not own or develop real estate.
- Ownership of certain assets is restricted, such as debts secured on foreign real estate or shares in non-Canadian corporations.
- No single shareholder (including related persons) can own more than 25% of our common shares.
- Cash on hand, debts secured on specified residential properties, and funds on deposit with Canada Deposit Insurance Fund or Régie de l'assurance dépôts du Québec-insured institutions or credit unions must make up at least 50% of our property's total cost for tax purposes.
- Real estate interest costs (excluding property acquired through foreclosure after default) cannot exceed 25% of our property's total cost.
- We have specific limits on our maximum debt-to-equity ratio.